Dell's 11% Slide: Barclays Says Enterprise AI Is Late, the Bond Market Says It's Expensive
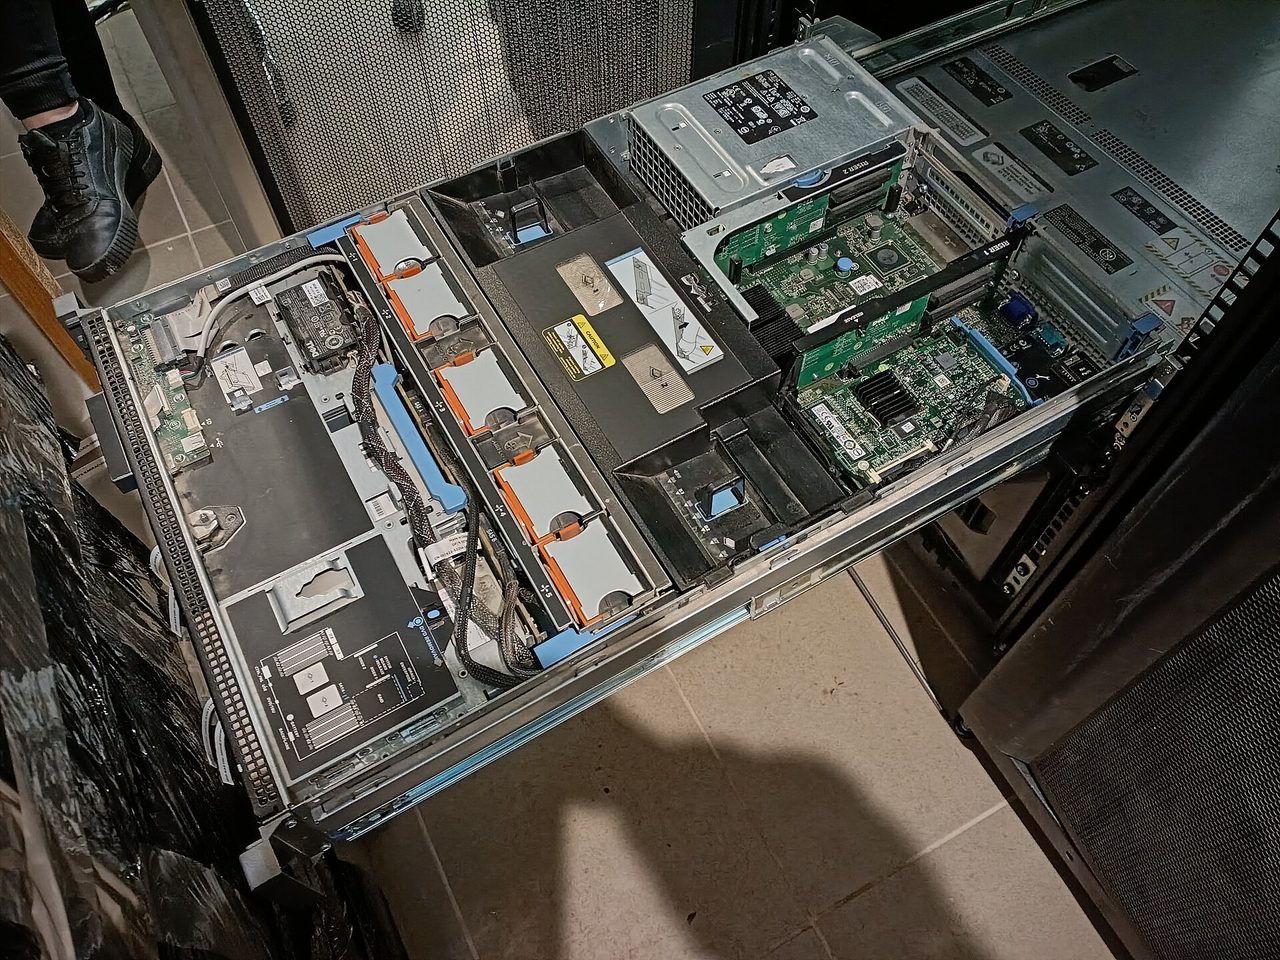
Photo: Cyber-Complex Foundation / CC BY-SA 4.0 · via Wikimedia Commons
Dell's 11% Slide: Barclays Says Enterprise AI Is Late, the Bond Market Says It's Expensive
Dell's worst day since April 2025
Dell Technologies fell about 11% on Wednesday, Oct. 14, touching an intraday low of $502.32 and closing near $506, down from the prior close of $572.47. CNBC put the decline at 11%; Reuters calculated 11.4%. Dow Jones data called it Dell's largest one-day percentage drop since April 2025, and one of the S&P 500's worst performers of the session. Volume ran about 11.6 million shares, roughly 40% above the 8.3 million average. All of it landed on a stock that had already gained more than 300% this year.
Three server makers, one downgrade
The trigger was Barclays. Analyst Tim Long cut Dell, Hewlett Packard Enterprise and NetApp to Equal Weight from Overweight, "after a significant run and on enterprise AI timing." He lowered his Dell target to $574 from $603 and his HPE target to $77 from $83, keeping NetApp at $219. Against Tuesday's close, the new Dell target implied just 0.3% upside, while the NetApp target implied 8.4% downside. Dell and HPE closed down 11.4% and 8.2% respectively, Reuters reported.
It's a valuation call, not a demand call
"Valuations have run, commodity costs have helped revenues, and we don't see a meaningful AI inflection yet," Long wrote. The seven enterprise-exposed names he covers are up about 140% on average this year against a 14% gain for the S&P 500, and trade around 21 times estimated 2027 earnings versus a five-year average near 15. Barclays is not disputing that AI demand exists — it is arguing the rally already priced in two years of it.
Memory inflation flattered the top line
Long's second concern is memory. Dell's beats have come largely from raising prices to absorb memory costs; the company's own guidance calls for just over 100% server revenue growth but only mid-teens growth in storage and client devices. He expects a "meaningful deceleration" as memory prices normalize, shrinking the size of future earnings beats. Industry data supports the worry: DRAM contract prices rose 90%–95% quarter over quarter in the first half of 2026, and TrendForce expects another 10%–15% increase in the fourth quarter.
Michael Dell: there isn't enough supply to be a bubble
A day before the downgrade, CEO Michael Dell pushed back on AI-bubble talk in a CNBC interview. "I don't think there's enough supply for it to be a bubble," he said — a new fab takes roughly four years, so fresh capacity may not arrive until 2029 or 2030, meaning "it will get worse next year." He also dismissed data center opposition as a major obstacle to 2027.
The numbers were genuinely strong
Dell's fiscal second quarter, ended July 31, showed revenue of $46.91 billion, up about 58% year over year, and non-GAAP EPS of $7.04, up 203%. Infrastructure Solutions Group revenue rose 89% to $31.8 billion, with operating margin up 620 basis points to 15%. AI servers set records across the board: $60.9 billion of orders, $16.4 billion of recognized revenue, and a $95 billion backlog — roughly 84% of the prior fiscal year's $113.5 billion in total revenue. Management raised full-year revenue guidance to $192 billion from $167 billion and AI server revenue guidance to $74 billion from $60 billion.
The selloff ran the whole stack
Dell wasn't alone. HPE fell 8.2%, Oracle 9%, and CoreWeave and Nebius fell between 9.5% and 16% depending on the quote. Data center operators Applied Digital and IREN dropped 8.8% and 9.9%. Together the declines erased roughly $80 billion in market value. The S&P 500 closed down 1.11% at 7,718.94, its biggest one-day drop since July 29, and the Nasdaq fell about 2%.
The deeper trigger was the cost of money
Blame the rating call alone and you miss the week. A hotter-than-expected US inflation print lifted rate-hike bets and sent the 30-year Treasury yield as high as about 5.61%. Debt-financed compute is the most exposed: the yield on $1.25 billion of CoreWeave unsecured bonds due 2032 touched 15% on Tuesday and closed at a record 14.5%. CoreWeave's five-year credit default swaps widened from 368 basis points on Oct. 6 to 643. In September, a 76-megawatt Virginia data center fully leased to CoreWeave sold $1.1 billion of high-yield bonds at a 9.25% yield, about 270 basis points above similarly rated debt.
Enterprise budgets are overrun; orders aren't there yet
This is the heart of the "enterprise AI timing" debate. Futurum's 2H 2026 survey of 1,636 technology decision makers found 46.9% of enterprises over budget on AI and only 5.6% under. BCG says AI's share of IT budgets has tripled from 5% to 17%. McKinsey counts just 6% of organizations as AI high performers. Barclays' read: customers are proving out AI on cloud capacity before buying their own infrastructure. The money is being spent — it just hasn't landed in Dell's order book.
Insiders sold into the rally
Disclosure filings added to the unease: Silver Lake-affiliated directors sold about $73 million of Dell stock on Oct. 6, and filings on Oct. 9 showed more than 119,000 shares sold, with some positions cut by half or more. Dell's market value stood near $338 billion intraday Wednesday, against an average analyst target in the $571–$594 range.
The next test is Nov. 24
Dell reports third-quarter results on Nov. 24. Three things to watch: whether enterprise orders shift from cloud to on-premises, whether the $95 billion backlog converts into cash flow given AI server margins near 5%, and how much of the pricing tailwind survives once memory costs roll over. The Street is already split — Mizuho at $650, Susquehanna at $700, TD Cowen at $550.
Sources
- CNBC
- Reuters
- Investopedia
- Yahoo Finance
- Morningstar