Why Smart Money Pays Hong Kong's Premium Banking Fees
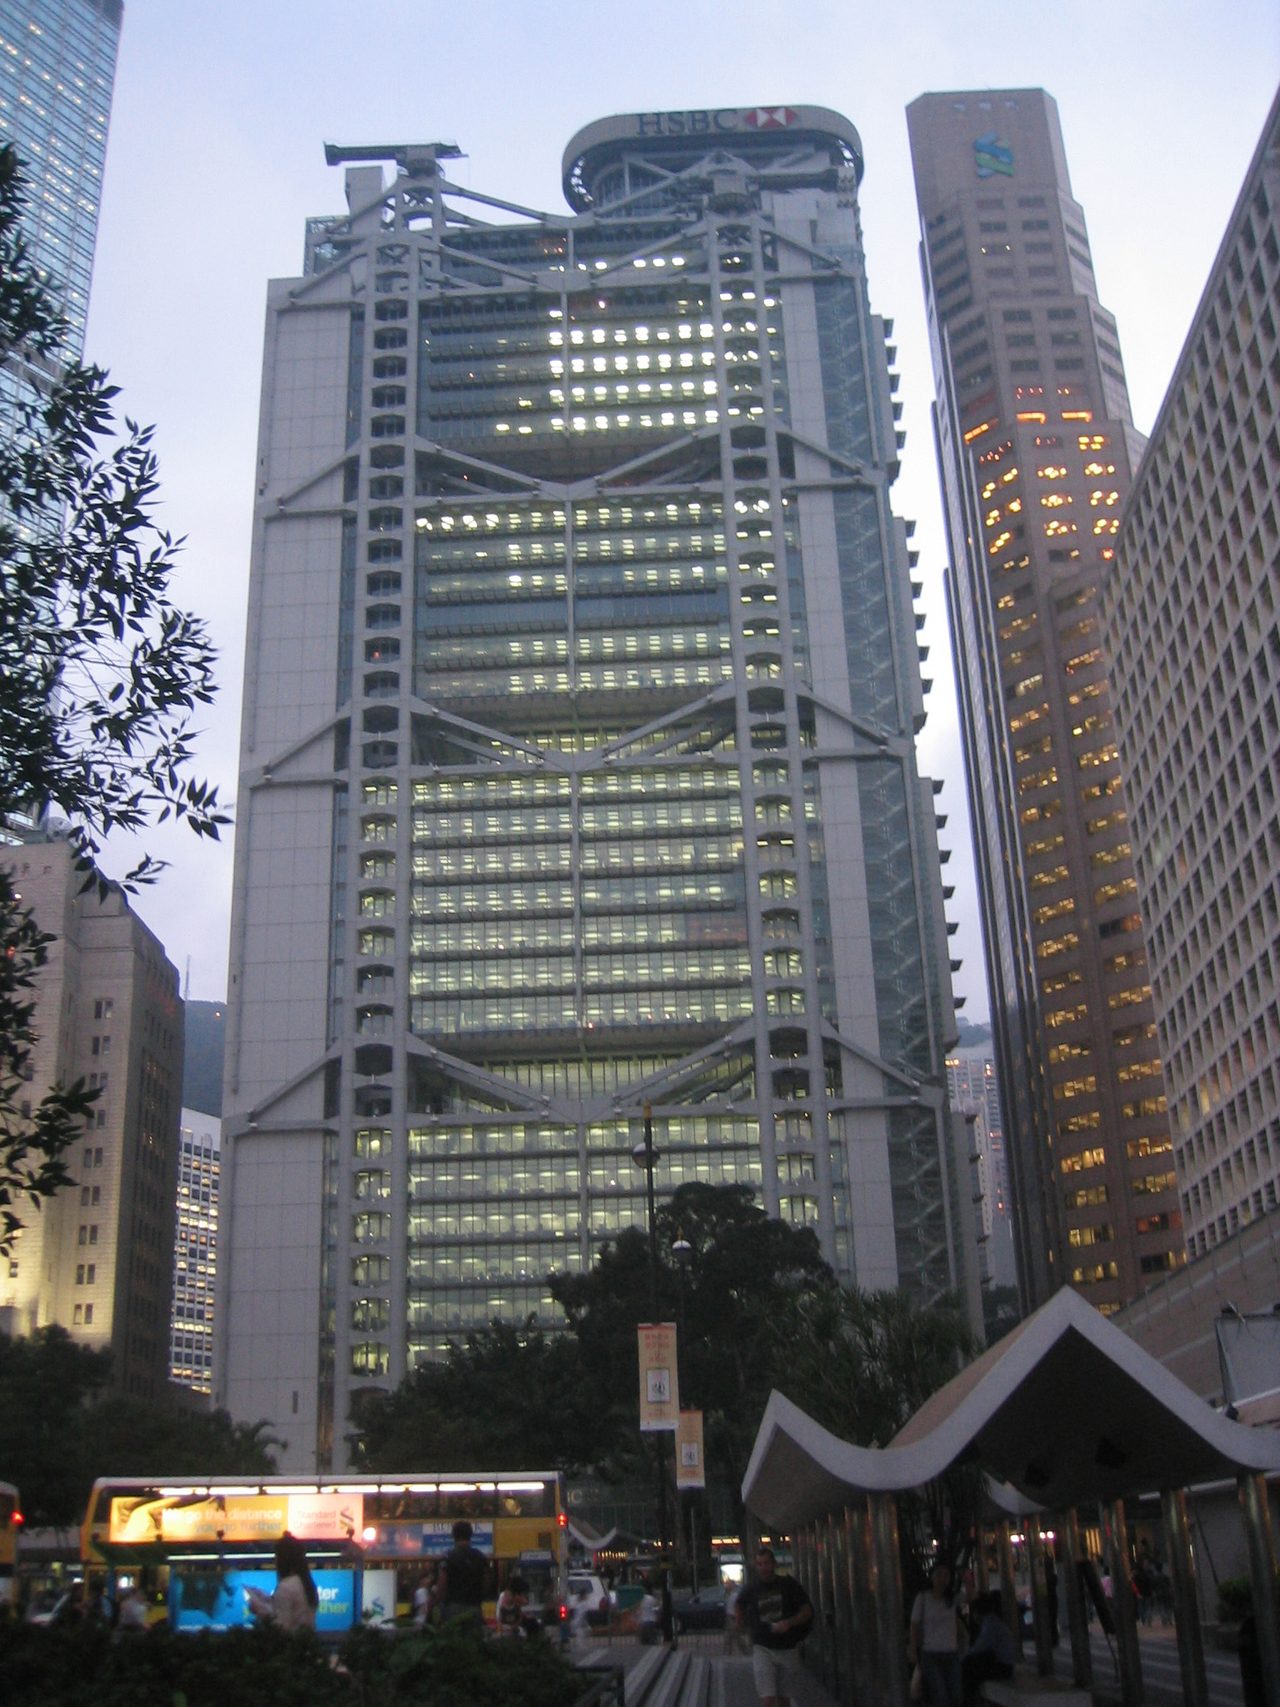
Photo: The original uploader was Louisehui at English Wikipedia. / CC BY-SA 3.0 · via Wikimedia Commons
Why Smart Money Pays Hong Kong's Premium Banking Fees
Deposits defy the fees, up 7.3 percent in a year
Hong Kong's banks are expensive, and the money keeps coming anyway. Figures released by the Hong Kong Monetary Authority on 30 September 2026 show total deposits at authorized institutions rose 1.4 percent in August and 7.3 percent from a year earlier. Hong Kong dollar deposits climbed 2.2 percent in the month and 8.6 percent year on year, while foreign currency deposits added 0.8 percent. The HKD loan-to-deposit ratio slid to 69.3 percent from 70.7 percent at end-July: deposits are growing faster than banks can lend them out.
A 0.95 percent rate sends mainland savers looking south
The push factor sits across the border. Since May 2025, China's five biggest state-owned banks have paid just 0.95 percent on a one-year term deposit, the first time the rate has fallen below 1 percent, with three- and five-year tenors at only 1.25 and 1.30 percent. With property values sagging and benchmark lending rates cut repeatedly since 2020, mainland savers describe a "deposit migration" out of near-zero-yield accounts into funds, insurance products and offshore assets.
The premium is real: minimums, monthly fees, wide spreads
Hong Kong banks charge for the privilege. Corporate accounts commonly demand minimum average balances, with monthly management fees for shortfalls. Cross-border remittances typically cost 0.1 to 0.25 percent of the amount plus a cable fee, and retail exchange rates often sit 2 to 4 percent below the mid-market rate. Major lenders such as HSBC suit high-net-worth clients; smaller businesses face onboarding scrutiny, waiting periods and fee tripwires that virtual banks and fintech accounts largely waive.
Three percent beats zero, and promos scream twenty
The interest-rate gap does the persuading. Plain Hong Kong dollar time deposits pay around 3 percent, with some six- to twelve-month products reaching 3.3 to 3.45 percent, while mainstream US dollar deposits fetch 3.6 to 4.3 percent. Promotional offers go much further: ZA Bank's seven-day FX-linked deposit advertises up to 20 percent annualized on renminbi and 17 percent on US dollars, and CCB (Asia)'s new-customer product offers up to 7.88 percent on Hong Kong dollars and renminbi and 8.88 percent on dollars, sterling and Australian dollars. Analysts caution these headline rates carry new-customer, fresh-funds and forced-conversion strings, but even the ordinary 3 percent dwarfs the mainland's 0.95 percent.
Wider doors: fund passports tripled, southbound flows doubled
Regulated channels have widened just as demand surged. Since January 2025, a Hong Kong fund may sell up to 80 percent of its assets to mainland investors, up from 50 percent. Pictet Strategic Income, domiciled in Hong Kong, grew from about 1.6 billion dollars to roughly 5.1 billion dollars in 2026, with about sixty percent of assets sourced from mainland buyers. Southbound Stock Connect average daily turnover reached HK$121.1 billion in 2025, more than double the HK$48.2 billion of 2024, accounting for about 24 percent of Hong Kong market turnover.
A 2.9 trillion dollar crown, built mostly on mainland money
The prize is scale. The Securities and Futures Commission reports total assets under management up 20 percent to HK$42.2 trillion, with private banking and wealth assets up 24 percent to HK$12.9 trillion on HK$2.1 trillion of net inflows. Boston Consulting Group data puts Hong Kong's cross-border bookings at about US$2.9 trillion in 2025, narrowly ahead of Switzerland, with mainland Chinese capital supplying over 60 percent. Add a record IPO pipeline, 116 listings raising more than HK$388 billion in nine months toward a possible HK$500 billion full year, and banks earn on every leg: deposits, conversions, subscriptions and underwriting.
Banks and brokers feast while compliance bills mount
The winners are licensed intermediaries collecting fees at each tollbooth. The risk is regulatory. Beijing has moved against unlicensed brokers serving mainland investors and, from 24 July 2026, imposed a 20 percent income tax on offshore trusts, with a 90-day regularization window closing on 22 October. Stocks of wealth-exposed giants such as HSBC, Standard Chartered, Prudential and AIA wobbled in June on fears of tighter controls. Hong Kong's deposit protection cap, raised to HK$800,000 in October 2024, covers small savers, but not currency losses or misuse of the US$50,000 annual foreign-exchange quota.
The window narrows, but the gateway has no rival
What comes next turns on three variables: whether the US Federal Reserve adds to its September 25-basis-point hike, which sets how long Hong Kong's rate premium lasts; whether southbound flows and the IPO boom sustain market turnover; and whether post-October trust-tax enforcement chokes or merely channels offshore demand. The fee gap will not close soon, yet neither will the logic sending money south: investors are not buying cheap banking, they are buying the ticket to global assets.
Sources
- Fintech Intelligence: Hong Kong Deposits Surge 7.3% Year-on-Year as HKMA Reports August Monetary Data
- China Banking News: China's deposit exodus and the transformation of banking system balance sheets
- finance.biggo.com: Hong Kong's High-Yield Time Deposits Hide a Catch: 20% Annualized Returns Come with FX Conversion Requirements and Marketing Gimmicks
- 利率20%的香港银行定存?需警惕高息揽客产品“赚息亏本”
- Citywealth: Hong Kong Overtakes Switzerland as China's Wealth Moves to the Next Generation