Net income rose 8.4% to $568.4 million. Diluted earnings per share came in at $0.29. Non-GAAP adjusted earnings were $0.30 per share.
Core Energy Beverage Segment Anchors Top-Line Expansion
The Strategic Brands division expanded 19.8%. This division encompasses acquired functional beverage product lines. It generated $156.4 million in quarterly revenue.
The Alcohol Brands division contracted 13.6% to $28.5 million. The decline reflects ongoing portfolio pruning. It also reflects distribution realignments in select regional markets.
Overseas Distribution Networks Deliver Record Volume Growth
International sales expansion was the primary growth catalyst in the third quarter. Net sales to customers outside the United States surged 28.1% to reach $1.20 billion. That represented approximately 47% of total consolidated net sales. The share was 43% in the third quarter of 2025.
Latin American territories recorded exceptional expansion. Net sales there posted a 48.8% increase in dollar terms. Strong consumer demand in Brazil primarily drove the gain. European, Middle Eastern, and Asia-Pacific operations also registered healthy double-digit shipment growth. Brand availability expanded across multi-lane grocery and automated retail channels.
Foreign currency translation effects contributed approximately $8.1 million to net sales during the quarter. Executive leadership confirmed during the earnings call that the company will continue allocating capital. The capital will expand local co-packing agreements across emerging markets in Southeast Asia and South America.
Input Inflation and Freight Pressures Narrow Gross Margin
Margin performance encountered modest headwinds from operational and raw material expenses. This came despite robust top-line momentum. Consolidated operating income climbed 6.4% to $718.7 million. That trailed the top-line growth rate due to higher cost of goods sold.
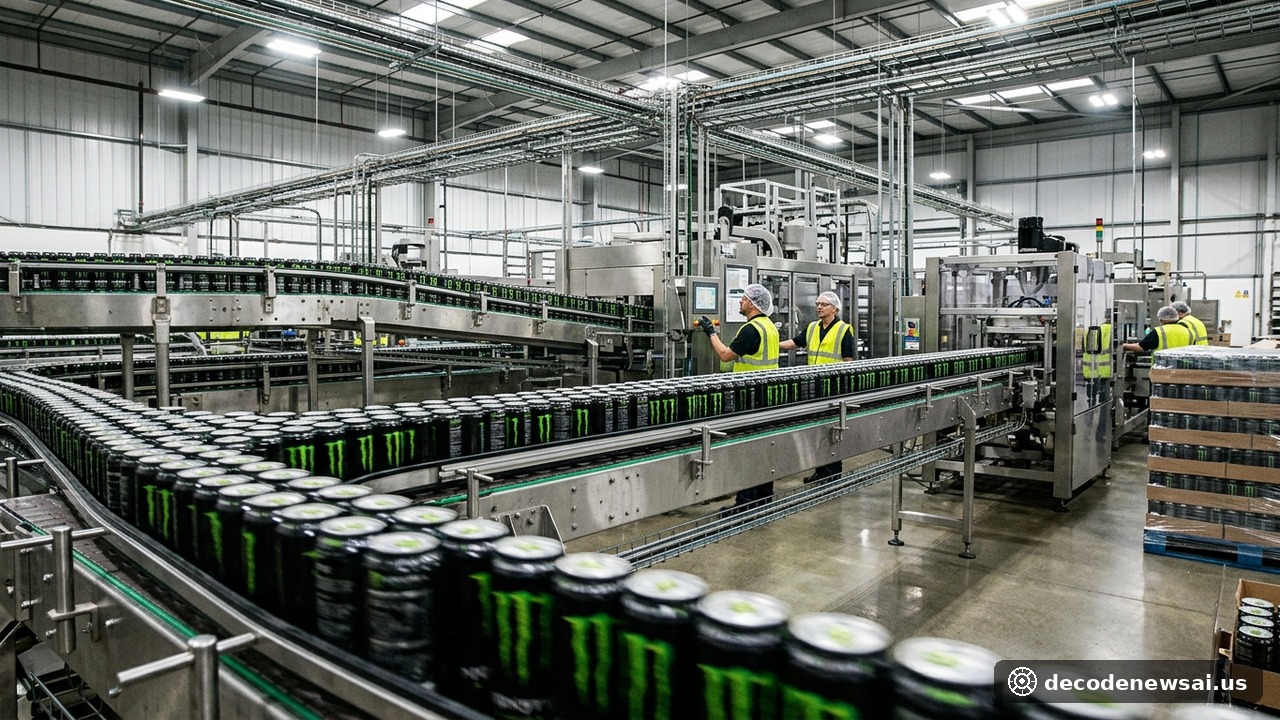
Gross profit margin contracted by 100 basis points. It declined from 55.7% in the prior-year quarter to 54.7%. Corporate filings attributed the margin compression to elevated aluminum beverage can pricing. Higher logistical and freight expenses also contributed. An adverse geographic product mix added to the pressure.
Operating expenses grew 24.2% year-over-year to $682.0 million. The expense increase included a $19.9 million non-cash property impairment. It also included $14.7 million in expenditures associated with enterprise digital transformation initiatives.
Robust Cash Reserves Enable Continued Share Repurchase Execution
During the third quarter, the company repurchased approximately 2.3 million shares of common stock. The average transaction price was $43.87 per share. Total repurchases came to roughly $100.0 million under its August 2024 share repurchase authorization.
As of November 4, 2026, approximately $800.0 million remained available for future open-market purchases. That capacity sits under authorized repurchase programs. Management reiterated that it will maintain disciplined capital allocation. It will prioritize strategic manufacturing investments and shareholder value creation.