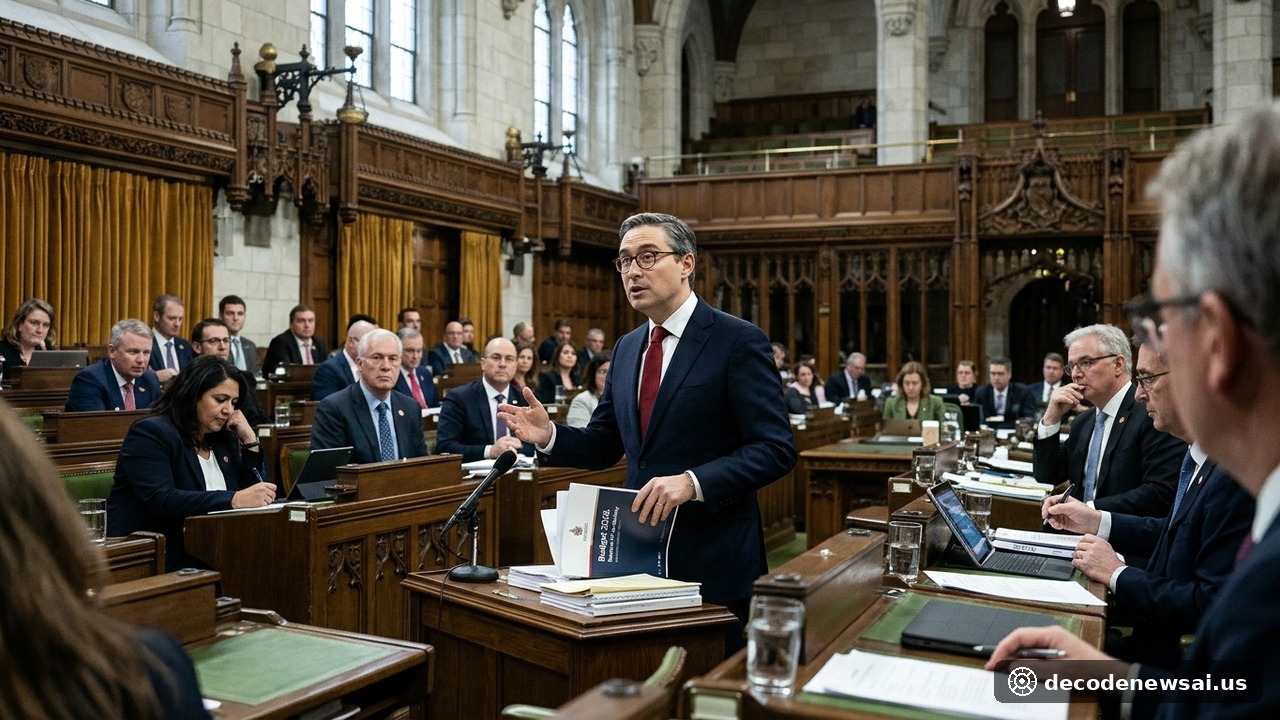
Canadian Deputy Prime Minister and Minister of Finance François-Philippe Champagne formally tabled the 2026 federal budget, titled "Masters of Our Destiny," before the House of Commons in Ottawa on November 5, 2026, unveiling a transformative economic blueprint to shield the nation against aggressive American tariff threats and international market turbulence. Backed by the Liberal government's commanding parliamentary majority, Champagne announced the launch of an ambitious "Investment Supercycle" designed to mobilize over $400 billion in public and private capital over six years across clean electricity grids, defense technology manufacturing, and critical mineral extraction, while projecting a disciplined fiscal deficit of $62.3 billion for the current fiscal cycle with a binding pledge to eliminate operational deficits by 2027–28.
What Are the Quantifiable Upstream Metrics and Tax Provisions in Canada's Budget 2026?
- Lifetime Capital Gains Exemption for Domestic Builders: Up to $15 Million CAD for Eligible Founders/Investors
On the corporate financing front, the budget initiates a sweeping merger of the Business Development Bank of Canada (BDC) and Export Development Canada (EDC) into a single, unified federal development finance bank tasked with extending patient equity and debt financing to capital-intensive industrial scale-ups.
How Does Sovereign Wealth Creation and Infrastructure Consolidation Restructure Growth?
Beyond targeted tax relief, Budget 2026 establishes unprecedented structural financing conduits designed to insulate high-growth technology enterprises against foreign capital flight.
The government authorized the creation of the $25-billion "Canada Strong Fund," a sovereign wealth investment vehicle that will take commercial equity positions in strategic domestic champions while offering retail "Canada Strong Notes" to permit citizen wealth participation. For high-growth digital sectors, Ottawa committed binding power offtake backstops securing 500 megawatts of clean electricity for sovereign AI compute facilities, ensuring domestic frontier laboratories remain anchored in Canada. Simultaneously, the Scientific Research and Experimental Development (SR&ED) tax incentive was expanded to allocate $930 million over five years toward commercialization, regulatory certifications, and patent filings.
Venture capital and private equity leaders across Canada welcomed the introduction of the Canada Growth Incentive, noting that personal capital gains tax exemptions are crucial for retaining high-growth technology founders within domestic borders. Historically, Canadian startups frequently relocated corporate headquarters to the United States prior to commercial scale-up phases to access deeper capital pools. By combining aggressive investment tax expensing with founder tax exemptions, Ottawa establishes competitive parity with Silicon Valley ecosystems.
Furthermore, the expansion of the SR&ED tax credit to encompass regulatory compliance and international intellectual property protection addresses a long-standing structural gap in Canadian innovation commercialization, allowing scaling firms to protect proprietary technologies in export markets.
What Are the Structural Implications for North American Trade and Canadian Sovereignty?
Minister Champagne's budget formalizes an epochal transition in Canadian economic policy, moving definitively away from consumption-oriented subsidies toward a muscular, supply-side industrial doctrine centered on domestic sovereignty.