What Are the Quantifiable Upstream Metrics and Subscription Benchmarks in Grindr's Q3 Release?
- Adjusted Operating EBITDA Profitability: $61.7 Million USD (43.7% High Adjusted Margin)
- Average Active Paying Users (APU) Base: 1.40 Million Paying Subscribers (+10.9% YoY)
- Average Revenue Per Paying User (ARPPU) per Month: Reached $27.15 USD (+10.0% Year-Over-Year Surge)
In an executive earnings webcast hosted by Chief Executive Officer George Arison and Chief Financial Officer John North, management detailed operational milestones underpinning the quarterly report. The company registered a GAAP net loss of $6.6 million, compared to net income of $30.8 million in the third quarter of 2025. This loss was governed entirely by extraordinary items, including a $33 million non-recurring litigation settlement charge resolving legacy pre-2020 UK consumer data claims without admission of liability, alongside $3 million in acquisition transaction fees. Excluding these specific items, normalized operational earnings stood at $21.0 million, reflecting robust underlying business cash conversion.
Operational metrics confirmed expanding monetization durability. The platform's paying subscriber base grew 11% to 1.4 million members, while blended monthly ARPPU expanded 10% to $27.15, validating the strong pricing elasticity of specialized subscription features.
How Does the $190M PurposeMed Acquisition and Edge AI Integration Unlock Compounding Growth?
The central strategic catalyst driving Grindr's medium-term expansion is its $190 million all-cash acquisition of PurposeMed, the parent entity behind leading North American virtual sexual health platform Freddie, which formally closed on November 2, 2026.
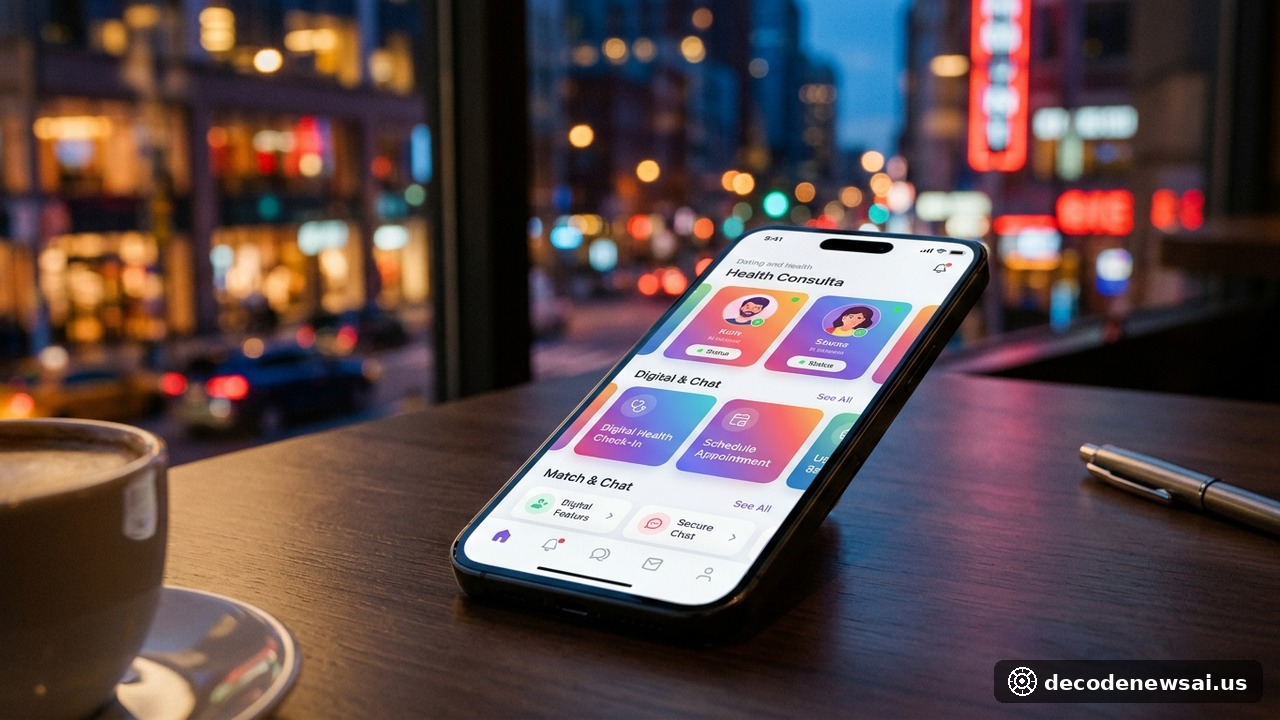
Arison noted to institutional shareholders that commanding 70 minutes of daily consumer attention positions Grindr to become an indispensable primary care conduit. By natively integrating Freddie's clinical consultations, lab screening workflows, and home-delivered pre-exposure prophylaxis (PrEP) pharmaceuticals into the core mobile interface, Grindr captures high-margin recurring healthcare revenue. Furthermore, management confirmed the upcoming November 17 global commercial launch of "Edge AI"—a premium subscription tier incorporating privacy-centric on-device machine learning agents designed to optimize user introductions, travel navigation, and local event curation.
Digital advertising strategists observed that Grindr's dual revenue architecture provides unprecedented resilience compared to legacy dating apps. While general market peers suffer from declining advertising click-through rates, Grindr's conversion of social interaction into essential medical consultations establishes a high-value monetization pathway. By providing localized health clinic locators and direct laboratory booking tools, the platform increases recurring subscriber retention across both urban and rural demographics.
Furthermore, management's conservative balance sheet management following the PurposeMed transaction was praised by equity research desks. The company's proactive debt paydown strategy and disciplined share repurchase program ensure that free cash flow is efficiently allocated to reduce interest expense while returning capital to long-term shareholders.
What Are the Strategic Implications for Global Vertical Social Networks and Digital Health?
Grindr's sustained 22% top-line acceleration illustrates a compelling structural blueprint for consumer software: transitioning highly engaged vertical affinity communities into comprehensive lifestyle and primary healthcare ecosystems.
Providing initial fiscal 2027 guidance forecasting annual revenue of at least $705 million and adjusted EBITDA of at least $275 million, Grindr is successfully decoupling its valuation multiples from conventional advertising-dependent social media platforms. By combining fortress recurring subscription cash flows with proprietary telehealth logistics, Grindr demonstrates that purpose-built vertical software ecosystems command unmatched customer loyalty, high barrier-to-entry moats, and durable multi-year compounding potential.