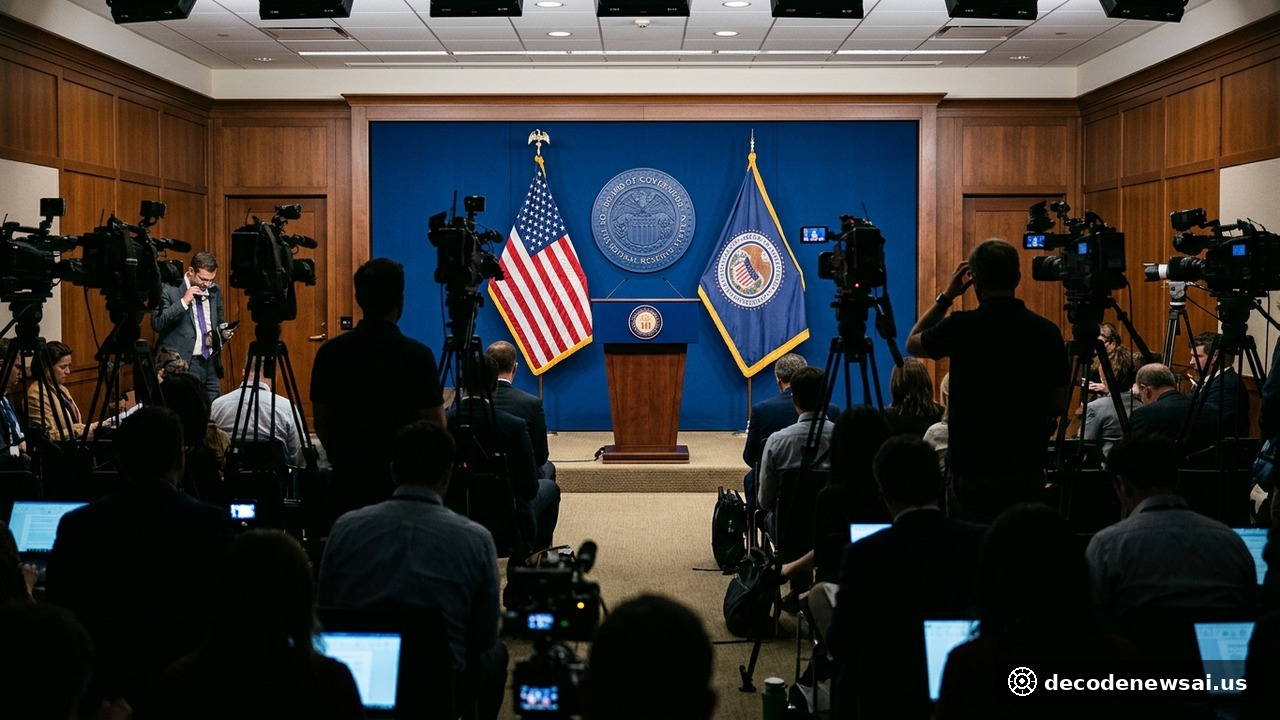
The Federal Reserve Board of Governors concluded its scheduled two-day Federal Open Market Committee (FOMC) monetary policy symposium on November 6, 2026, officially issuing its policy determination to maintain the benchmark federal funds rate target range at 3.75% to 4.00%. The policy pause aligned with broad consensus expectations across Wall Street primary dealers. During the post-meeting press briefing, Federal Reserve Chair Jerome Powell delivered resolute macroeconomic remarks, underscoring that while recent post-election nonfarm payroll releases confirm exceptional labor market durability, core Personal Consumption Expenditures (PCE) inflation continues to exhibit persistent resistance above the 2.0% statutory mandate. Emphasizing that policymakers require unambiguous evidence of structural disinflation before endorsing consecutive policy accommodation, Chair Powell reinforced an enduring higher-for-longer policy trajectory amid expansionary fiscal deficits.
Key Monetary Policy Benchmarks: November 2026 FOMC Determination
- Federal Funds Target Policy Rate Range: Maintained at 3.75% to 4.00% (Effective Rate ~3.88%)
- FOMC Board Policy Voting Distribution: 10 In Favor of Pause; 2 Dissents Favoring Hike
- Core PCE Price Deflator (Trailing 12-Month): +2.8% Annualized Rate (Above 2.0% Objective)
- Balance Sheet Quantitative Tightening (QT): Continuing Monthly Cap of $60 Billion Roll-Off
Why Did Resilient Employment Data Justify a Hawkish Monetary Pause?
Navigating the delicate transition toward long-term price stability, the Federal Open Market Committee encountered diverging economic telemetry. October's establishment employment survey documented job creation numbers that exceeded macroeconomic forecasts, while the headline unemployment rate settled at a historically low 4.1% and average hourly earnings maintained steady year-over-year growth of 3.8%.
Addressing reporters, Chair Powell asserted that robust labor dynamics confirm the domestic economy continues to operate near potential capacity, eliminating imminent risks of a hard-landing recession. However, vigorous consumer expenditure within services sectors continues to impede the final phase of inflation normalization toward 2.0%. Premature monetary easing carries severe risks of reigniting speculative asset bubbles across commercial equity and residential real estate markets, reminiscent of destructive stop-and-go monetary cycles observed during the late 1970s. Consequently, maintaining restrictive borrowing costs represents the prudent strategy to guarantee long-term price stability.
What Underpinned Two Rare Dissents Favoring an Immediate Rate Hike?
In an unusual departure from committee consensus, the November policy vote was not unanimous. Two regional Federal Reserve Bank presidents entered formal dissenting votes, arguing that economic conditions warranted an immediate 25-basis-point increase to constrain emerging inflationary impulses. This represents the first dual hawkish dissent recorded since the central bank reached its restrictive platform.
Dissenting policymakers expressed grave concern regarding post-midterm fiscal trajectories. Across Capitol Hill, legislative expenditures on defense rearmament, industrial supply-chain repatriation subsidies, and municipal transfers continue to sustain an expansionary federal deficit exceeding 6% of gross domestic product. This persistent fiscal stimulus, coupled with resilient private-sector capital demand, has elevated the neutral rate of interest (R-star). In the assessment of the hawkish minority, holding policy rates within the 3.75%–4.00% corridor leaves monetary conditions insufficiently restrictive to definitively eliminate secondary inflation pressures.
Where Are Global Bond Yields and Capital Flows Heading Into 2027?
Multinational macro strategists at the International Monetary Fund (IMF) observe that prolonged monetary divergence between the Federal Reserve and international central banks—particularly the European Central Bank and the Bank of England, which have commenced easing cycles to counter domestic economic stagnation—is placing sustained depreciation pressure on non-dollar currencies. Widening trans-Atlantic yield spreads continue to attract cross-border liquidity into high-yielding dollar assets, presenting emerging market sovereigns with elevated refinancing hurdles as global financial conditions tighten into 2027.