The California Air Resources Board (CARB) formally finalized regulatory implementation milestones for the state's landmark Climate Corporate Data Accountability Act (SB 253) on November 10, 2026. The agency established strict reporting timelines requiring large corporations operating within California to quantify, verify, and publicly disclose their Scope 1 direct operational emissions and Scope 2 purchased electricity emissions, maintaining the statutory reporting framework despite intensive corporate lobbying. Establishing Strict Deadlines for Scope 1 and Scope 2 Emissions Reporting Under SB 253 The regulatory announcement formalizes compliance obligations for thousands of public and private companies doing business in California with annual global revenues exceeding one billion dollars.
CARB mandates third-party assurance and fifty thousand dollar penalties
Under the adopted implementation schedule, covered entities must submit their comprehensive Scope 1 and Scope 2 greenhouse gas inventories to the state reporting portal no later than the newly designated annual deadline. Scope 1 metrics encompass direct emissions generated from stationary fuel combustion, company-owned vehicle fleets, and on-site industrial manufacturing. Scope 2 requirements compel organizations to report indirect emissions associated with purchased electricity, steam, heating, and cooling consumed during the preceding fiscal year.
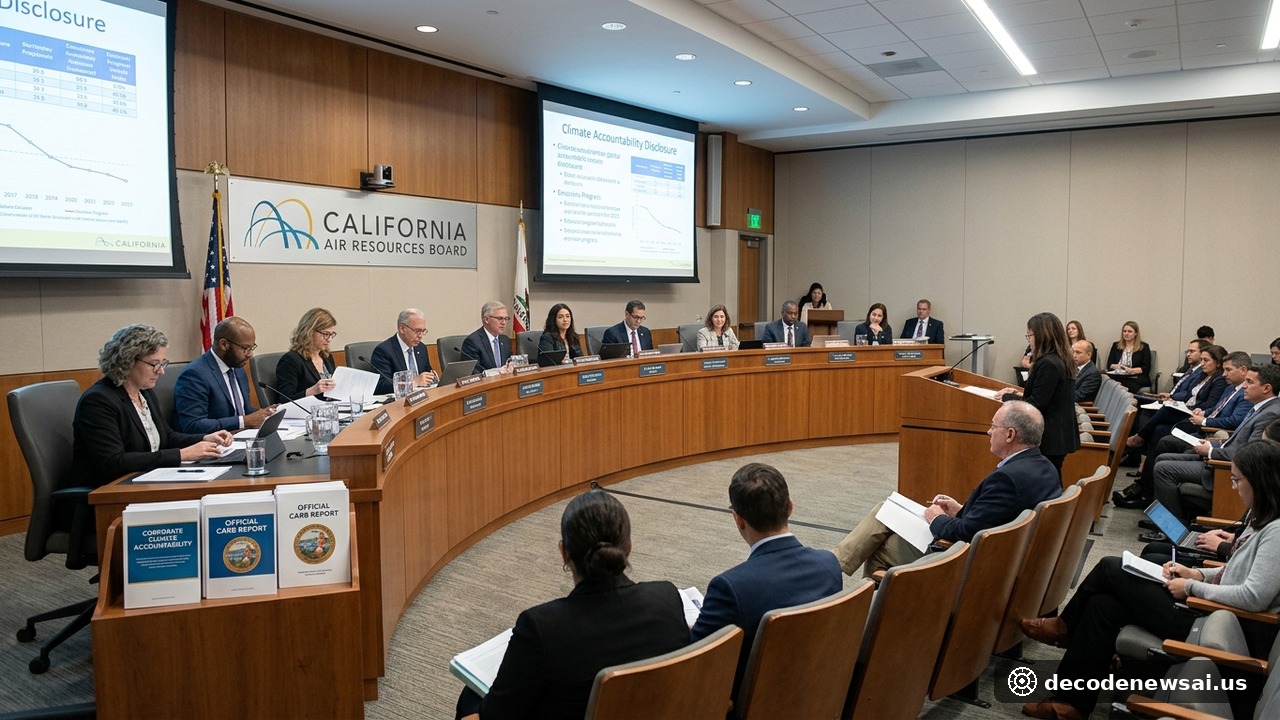
The Executive Officer of the California Air Resources Board stated during a public hearing in Sacramento: "Establishing clear, non-negotiable compliance deadlines for Scope 1 and Scope 2 carbon disclosures represents a transformative step toward corporate climate transparency. Standardized emissions accounting equips consumers, investors, and regulators with the verified factual baseline needed to accelerate meaningful industrial decarbonization." Mandating Independent Third-Party Assurance Protocols to Guarantee Data Integrity To ensure corporate filings reflect genuine operational performance rather than promotional claims, CARB enacted comprehensive third-party auditing requirements.
Beginning with initial reporting cycles, corporate filings must include limited assurance statements issued by accredited independent auditing firms. The regulatory framework establishes rigorous standards governing auditor competence, conflict-of-interest prohibitions, and evidence-gathering methodologies. Regulators warned that intentional underreporting or willful omissions will trigger civil enforcement penalties of up to fifty thousand dollars per day of violation.
CARB outlines phased Scope 3 disclosures and technical guidance
A senior environmental regulatory partner at a prominent corporate law firm commented in San Francisco: "CARB's finalization of Scope 1 and Scope 2 reporting schedules leaves no doubt regarding California's determination to enforce emissions transparency. Corporate boards must immediately formalize internal climate governance and retain qualified independent assurance providers." Outlining Phased Scope 3 Value Chain Disclosures and Technical Guidance for Reporting Entities In addition to finalizing direct emissions deadlines, CARB provided updated technical guidance outlining the subsequent phase-in of Scope 3 supply chain disclosures scheduled for subsequent reporting cycles.
The agency released detailed emissions calculation guidance, sector-specific emission factor databases, and standardized electronic reporting templates to assist compliance teams. State officials emphasized that the regulatory framework aligns closely with the Greenhouse Gas Protocol Corporate Standard, ensuring multinational enterprises can utilize harmonized emissions data across international reporting jurisdictions.
The Executive Director of a statewide sustainable business coalition observed: "California has successfully converted voluntary climate declarations into enforceable balance sheet realities. Reliable carbon data reporting will channel billions of dollars in private capital toward genuinely low-carbon business models."
Advisors note predictable frameworks and 2027 implementation milestones
Strategic planning advisors and international trade specialists noted that long-term intergovernmental frameworks generate predictable operating environments across key industry sectors. By coupling transparent administrative guidelines with rigorous scientific benchmarks, regulatory bodies and enterprise leaders establish sustainable operating models capable of withstanding shifting macroeconomic dynamics. Global market participants will continue observing forthcoming implementation milestones as public agencies execute their mandated responsibilities throughout 2027. Cross-border coordination remains vital for driving sustained operational resilience and delivering measurable societal benefits worldwide.
Strategic planning advisors and international trade specialists noted that long-term intergovernmental frameworks generate predictable operating environments across key industry sectors. By coupling transparent administrative guidelines with rigorous scientific benchmarks, regulatory bodies and enterprise leaders establish sustainable operating models capable of withstanding shifting macroeconomic dynamics. Global market participants will continue observing forthcoming implementation milestones as public agencies execute their mandated responsibilities throughout 2027. Cross-border coordination remains vital for driving sustained operational resilience and delivering measurable societal benefits worldwide.