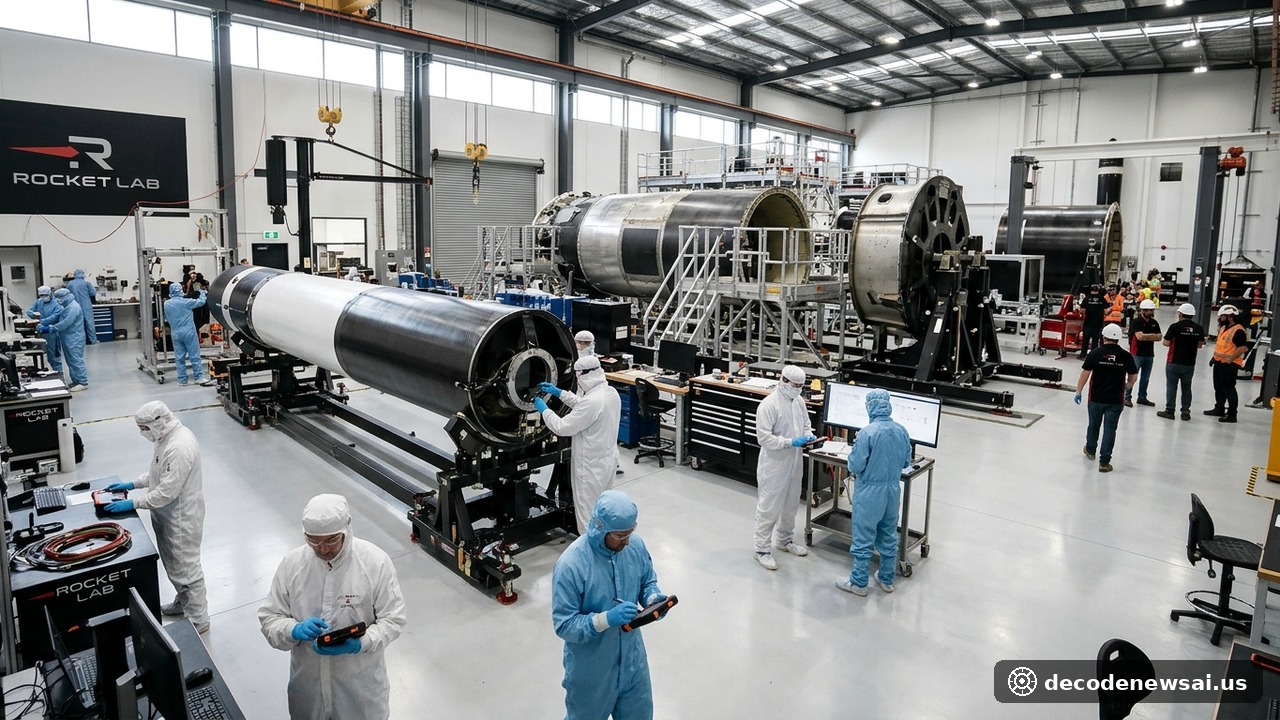
Rocket Lab Corporation on Monday reported third-quarter 2026 financial results after market close, delivering record revenue alongside surging customer demand. Fueled by high-frequency Electron orbital missions and expanding Space Systems manufacturing volume, quarterly revenue climbed to $268 million, marking the highest single quarter in the company's operating history. Total unfulfilled order backlog expanded 52% sequentially to $3.57 billion. Commercial aerospace fundamentals in the United States continue to strengthen. Wall Street trading reflected heightened volatility.
High Launch Cadence and Space Systems Delivery Propel Top-Line Growth
Third-quarter revenue reached $268 million, representing a 73% year-over-year increase compared to $155 million in the third quarter of 2025. That total surpassed consensus analyst projections of $257.17 million. Revenue expanded by $34 million sequentially over the second quarter, marking the company's sixth consecutive record revenue quarter. Space Systems manufacturing operations generated $197 million, functioning as the primary cash-generating foundation for the enterprise. Launch services and satellite manufacturing segments operated with effective alignment. The integrated commercial space model is yielding tangible returns.
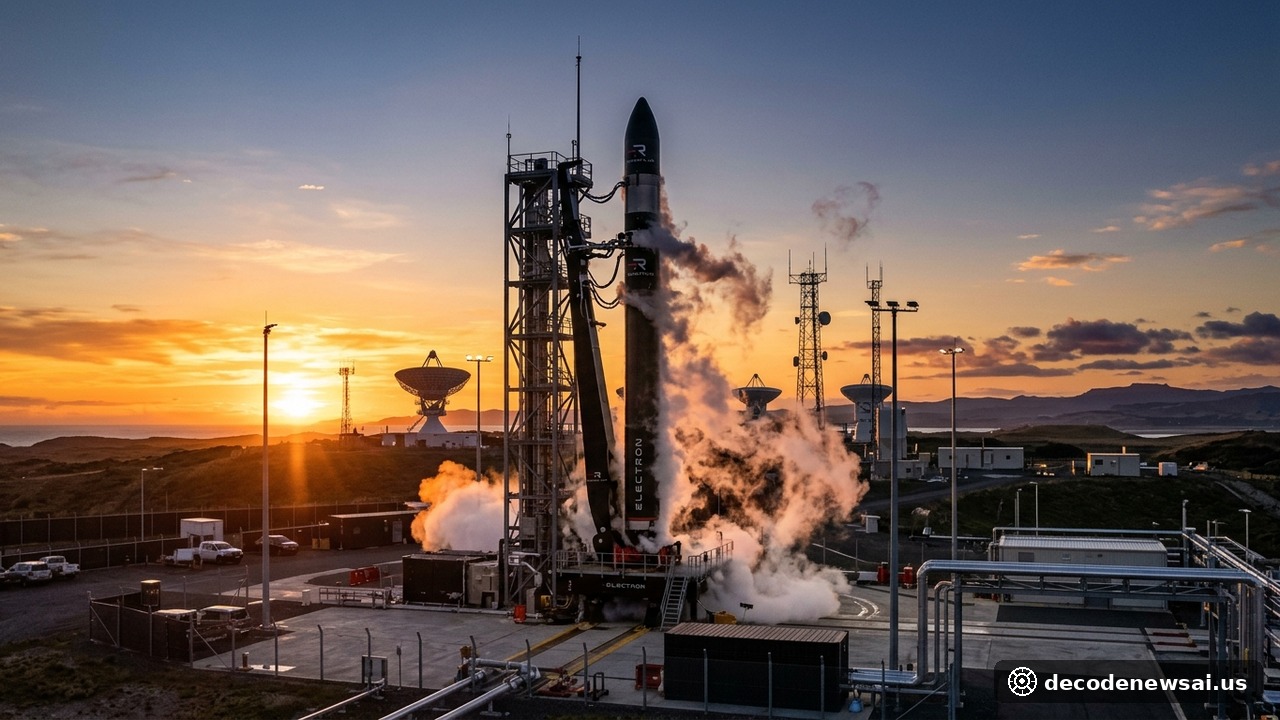
Within launch operations, the flagship Electron light orbital launch vehicle maintained sustained mission execution throughout the quarter. Rocket Lab has completed 99 successful Electron launches to orbit, preserving its standing as the second most frequently launched orbital rocket in the United States. Average contract pricing per Electron launch held steady at approximately $8.2 million. Launch unit margins remained consistent. Commercial orbital demand demonstrated enduring resilience.
Rocket Lab founder and chief executive officer Sir Peter Beck summarized operational milestones in the official earnings release. He stated: "Q3 2026 was a defining quarter for Rocket Lab. We delivered a record $268 million in revenue ($34 million higher than Q2 2026) alongside a record backlog which has grown to $3.57 billion. Nearly $1 billion of that backlog comes from new launch contracts, signed in Q3 2026 alone, as well as $470 million signed for Space Systems." The investor conference call drew widespread market attention. Corporate leadership voiced confidence in vertically integrated capabilities.
Medium-Lift Neutron Rocket Wins Over $515 Million in Commercial Constellation Deals
Backlog expansion represented the standout operational metric within the third-quarter earnings disclosures. Total customer commitments surged from $2.37 billion at the end of June to $3.57 billion, adding $1.2 billion in sequential net backlog. The medium-lift, reusable Neutron launch vehicle captured substantial customer interest from global satellite constellation operators. Third-quarter Neutron launch commitments exceeded $515 million, expanding the vehicle's firm mission manifest to 16 planned orbital flights. Constellation deployment pipelines offer substantial commercial runway. Market barriers to entry continue to rise.
The Neutron launch vehicle is designed specifically to serve mega-constellation deployment and heavy commercial satellite logistics. The maiden flight test remains scheduled for 2027, with full-system hot-fire trials of the Archimedes engine completed at launch facilities in Virginia. Deploying Neutron commercially could challenge established heavy-launch monopolies across commercial orbital transportation. Emerging launch capacity remains severely constrained. Industrial aerospace engineering is advancing rapidly.
Rocket Lab achieved positive GAAP operating cash flow during the third quarter, marking an important operational milestone. The improvement reflects strengthening cash generation across mature manufacturing and flight lines. Cash, cash equivalents, and marketable securities totaled $580 million at the end of September. Ample balance sheet liquidity provides robust operational runway for Neutron infrastructure scaling. Credit rating agencies affirmed the company's sound liquidity profile.
Sustained Research Spending Expands Quarterly Loss as Stock Swings After Hours
Despite reaching record revenues and historic backlog levels, third-quarter net losses widened year-over-year due to elevated capital expenditures. The company reported a GAAP net loss of $64 million, equating to a loss of $0.12 per share, wider than analyst consensus forecasts anticipating a loss of $0.07 per share. Loss expansion was driven primarily by tooling investments for Neutron production and intensive Archimedes testing programs. Research spending remained heavy. Sustainable profitability will require broader production scaling.
Shares of Rocket Lab surged 10.91% during regular Monday trading to close at $58.86. Following the earnings release, shares dropped 6.52% in after-hours trading to $55.02 as investors weighed top-line outperformance against the wider-than-expected quarterly loss. Trading volume was heavy. Market participants engaged in vigorous debate over capital expenditure burdens versus long-term constellation value.
Management issued optimistic guidance for the fourth quarter of 2026. The company expects fourth-quarter revenue between $270 million and $290 million, with gross margins widening between 34% and 36%. Hitting those guidance targets would position full-year 2026 revenue near the $1 billion milestone. The commercial space sector is transitioning from speculative narratives into industrial revenue reality.